

About the lender
The lender is one of India's leading digital lending platforms, offering a wide range of loans from personal loans to auto loans through a fully digital experience in tier 1 and tier 2 cities.
Once accounts flow down the buckets, primary numbers no longer respond, RPC and borrower intent drastically reduce, and every call driven by a human advisor gets expensive.
What was troubling the lender wasn’t "how do we collect?", it was "who is even contactable, and who is ready to settle?"
What was slowing down collections?
While running campaigns for the NPA bucket, the strategy shifts fundamentally from the borrowers in early delinquencies. The probability of contactability and, hence, collections from these borrowers moving into deeper delinquencies reduces significantly. This results in lenders deploying more advisors to reach and contact more borrowers and for higher efficiencies. But this efficiency comes at a linear increase in cost. For advisors, the process involves reaching out to all borrowers one by one, finding out their willingness to pay, and the biggest drop-offs in the funnel.
In short, the real job then becomes finding the few borrowers worth a collection inside a very large base.
That created a set of hard problems for the lending institution:
- Coverage at scale: The NPA base was too large for any human calling team to sweep at a sensible cost and fast without any delays.
- Low connectivity on primary numbers: Connect rates on primary numbers in this bucket typically sit at anywhere below 6%, so most dialling time goes to calls that never connect and convert.
- No intent signal: From those 6% who picked up the call, agents never knew which borrowers were willing to settle before dialling, so high-intent and zero-intent accounts got the same effort.
- Stale contact data: Many borrowers were only reachable on alternate numbers, which needed right-party contact (RPC) checks before an agent could engage.
- Costly human effort: Daily, the most productive hours of every agent were spent on unreachable or unwilling borrowers, which led to no recovery.
Hence, what was needed was not another calling vendor, but an intelligence layer that could cover the entire base and hand agents only the conversations worth having.
The Solution: DPDzero's Approach
DPDzero deployed its Voice AI agent across the lender's NPA book, not as a direct collections tool, but as a coverage and intelligence engine.
Voice AI became the lead generation and prioritisation layer that swept 100K+ accounts each day to find out who is reachable, who is ready to settle, and to capture disposition.
Voice AI’s NPA Settlement Bot ran across the lender's NPA portfolio in early October 2026. The goal was not to close deals on the call. It was to identify who picks up, who is willing to talk, and who shows settlement intent.
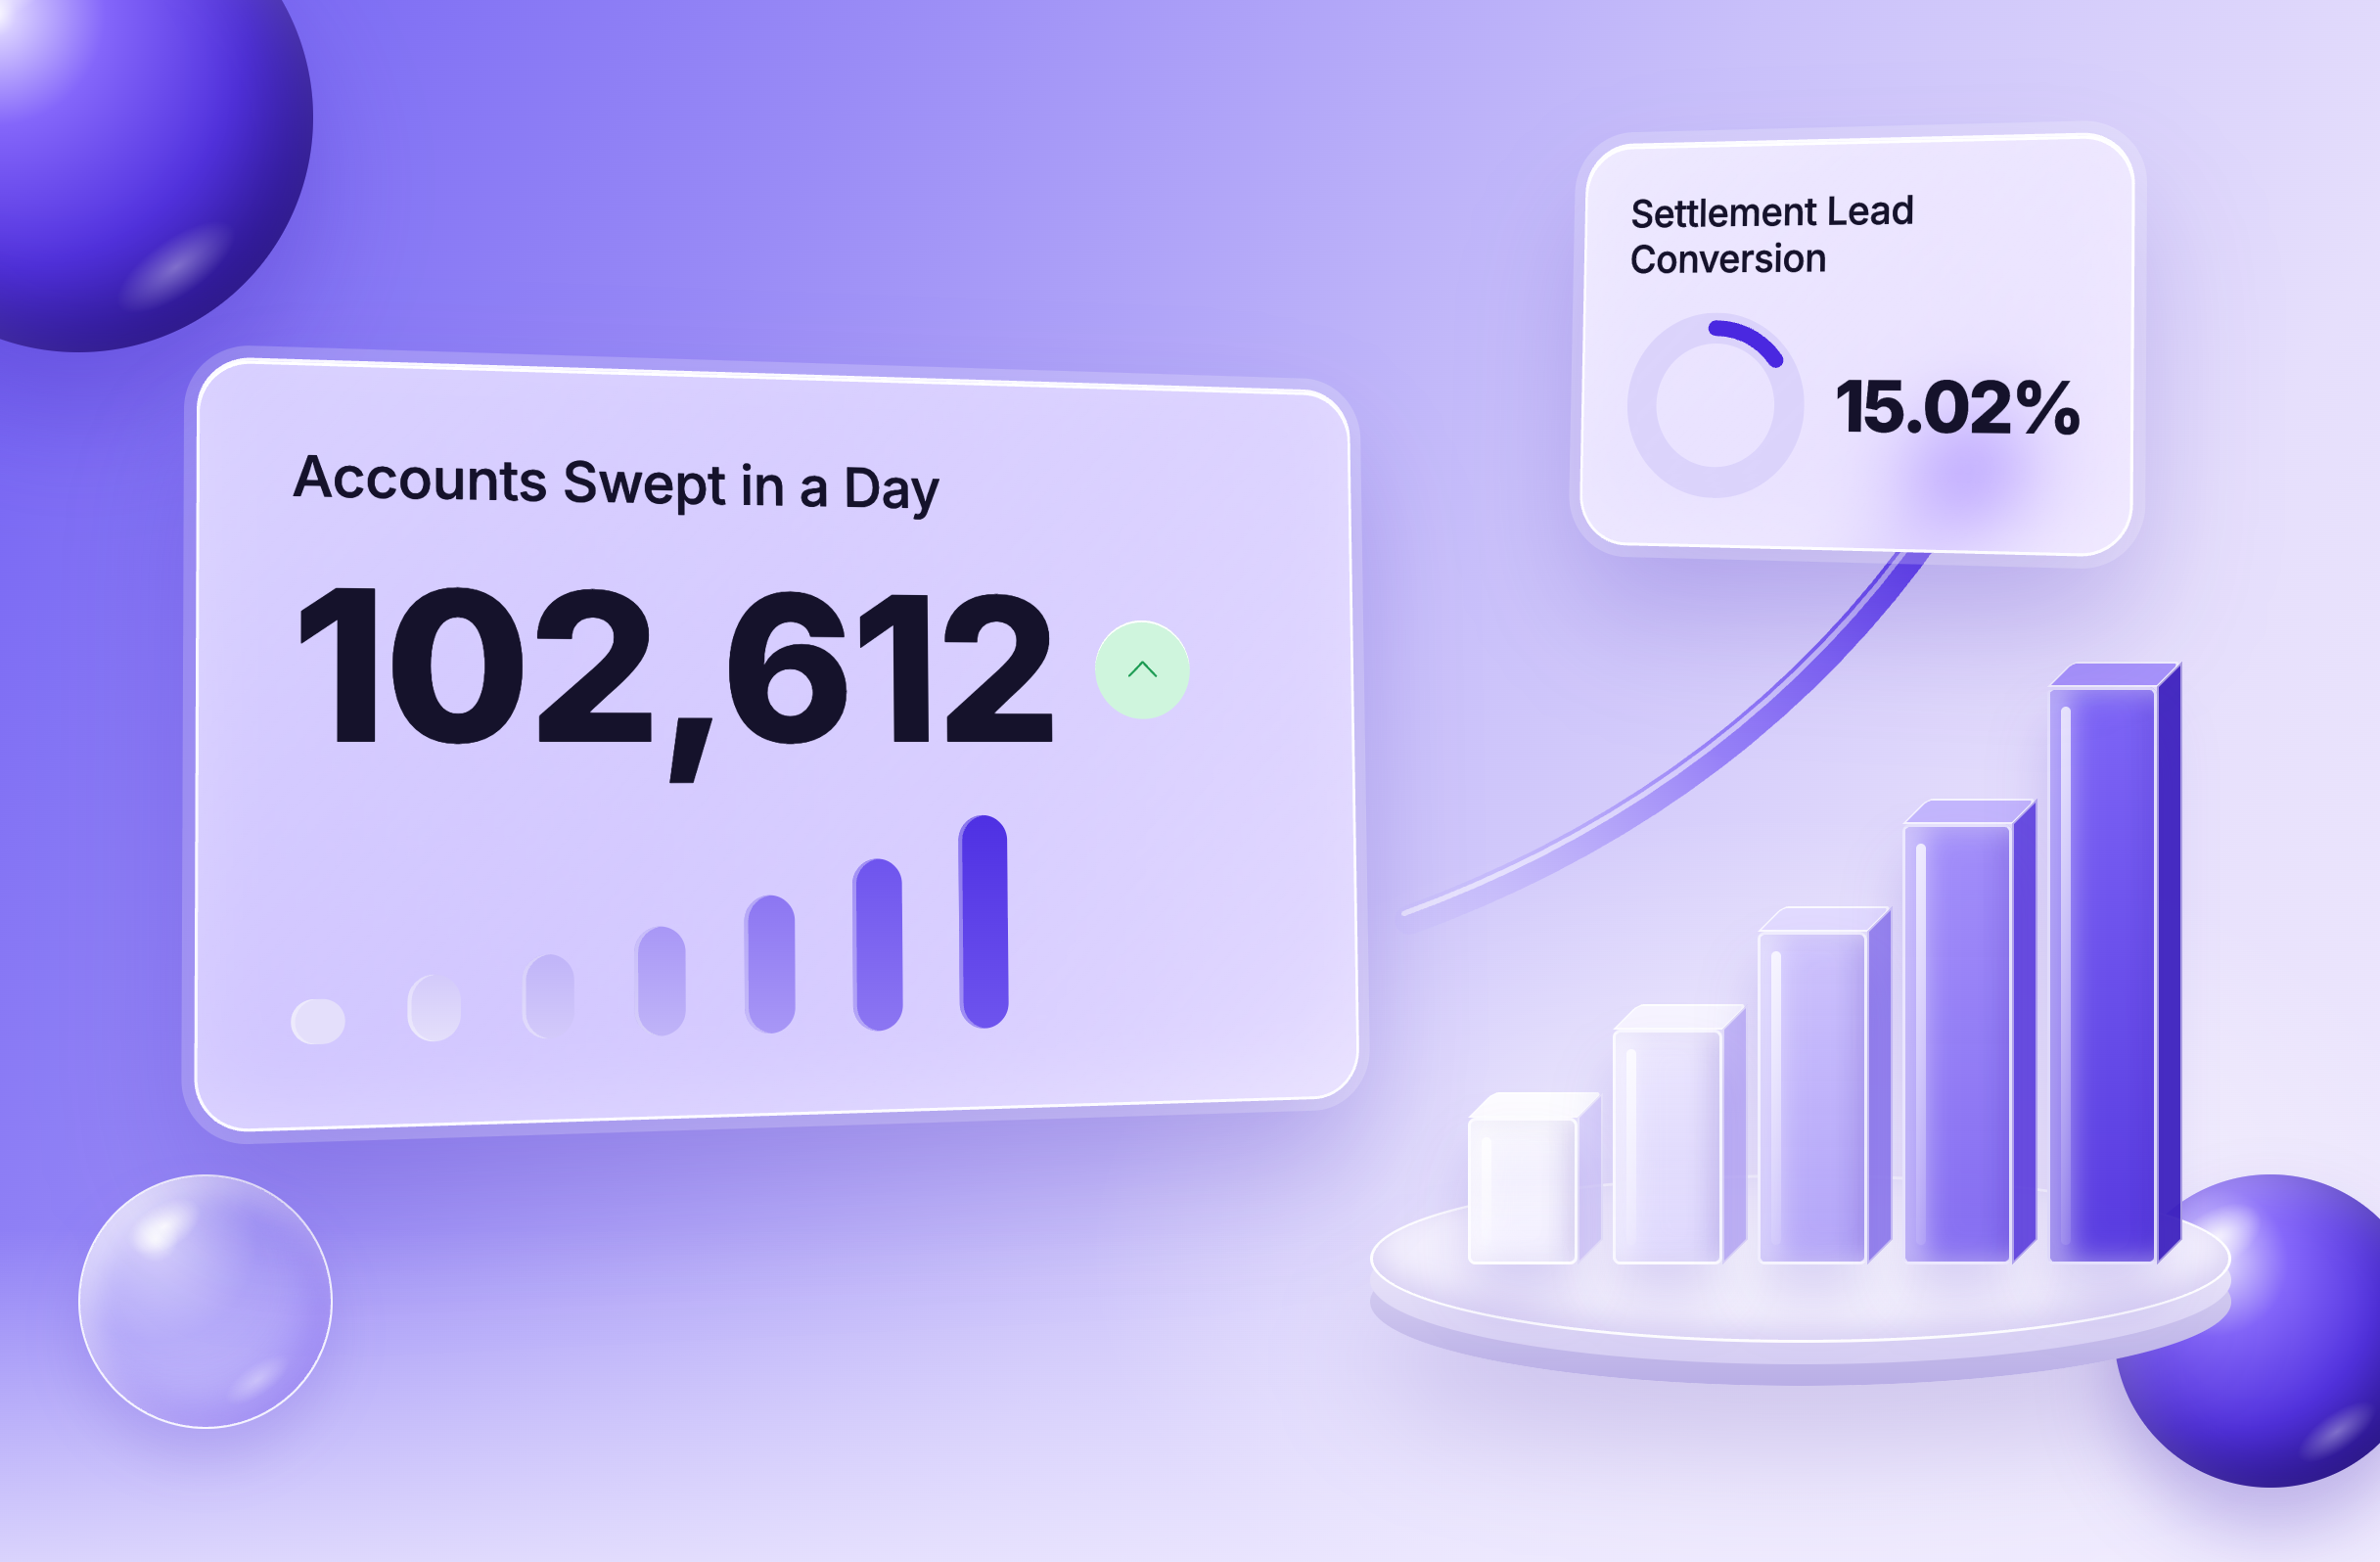
On 18 October alone, DPDzero’s Voice AI swept 102,612 unique accounts, a scale impossible for any human calling team at comparable cost. The value is in the leads generated: 7,090 settlement leads in a single day.
Impact on Human Advisor calling on Voice AI-generated leads
Once Voice AI identifies leads, human advisors take over. 2 types of leads are passed on to human advisors:
Calling on Alternate Numbers: RPC and Priority Leads
Voice AI flags borrowers who can’t be reached on their primary number. It then reaches out to the alternate numbers to check Right Party Contact, and ranks them by priority. Human advisors then work on these leads, get in touch with them, and try closing the collections loop.
Calling on Settlement Bot Leads: Settlement Intent
Many borrowers communicate to our Voice AI that they are willing to settle. So agents start the call with a strong payment intent and go straight to terms. Settlement leads generated by the bot usually do a better job at closing collections than the alternate-number calls.
The Intersection Point
The funnel is clear: Voice AI covers the base → identifies settlement-ready borrowers → human advisor closes at a 10- 15% success rate.
The best part? Not replacing the human, but ensuring the human only talks to borrowers ready to resolve, thereby amping up the efficiency of the whole collections engine
"DPDzero's Voice AI changed how we work our NPA book. Instead of dialling blind, human advisors now start their day with borrowers who have already shown they're ready to settle."
Spokesperson, Leading Digital Lender
What Did DPDzero Achieve for the Lender
- 15.02% Settlement lead conversion
- 7,090 Voice AI-identified Settlement leads in a single day
- 102,612 Unique accounts swept in a single day
Operational Outcomes
- Entire NPA base covered on primary numbers within hours of allocation
- Settlement intent pre-qualified by AI before human outreach
- Dispositions captured on every connected call
- Clear split of leads into RPC/priority and settlement tags
- Human agents focused on high-probability leads instead of cold dialling
Results & Impact
Voice AI-generated settlement leads convert at 15.02%, leading to 24.53 lac more in collections in a month: the single highest efficiency number in the entire NPA calling operation. Without Voice AI, these leads wouldn’t have existed. Even with the same borrower cohort, when performed by Voice AI and human advisors separately, different outcomes are seen when intent is pre-qualified by AI.
Hence, when accounts flow into deep delinquency stages, the playbook changes. What differentiated DPDzero was not just the numbers, but the ability to operationalise:
- Voice AI as a coverage and intelligence layer, not just a dialler
- Intent-based lead routing to human agents
- A clean handoff between AI and human calling teams