

About the lender
The lender is one of India's fast-growing digital lending platforms, offering personal loans through a fully app-first experience, from application to disbursal to repayment.
The borrowers largely span across urban areas and are often salaried: office staff, gig workers, and part-time professionals whose repayments move in step with their monthly paycheque.
With lakhs of active loans across regions and very different repayment habits from city to city, keeping repayments on time and stopping accounts from slipping into later buckets is a daily operational challenge. Solving it at scale needs collections that are proactive, tech-led, and built to grow with the book.
What was slowing down collections?
The lender’s borrower base largely consists of urban working-class customers whose repayment behavior is highly dependent on salary cycles. Since a significant portion of their monthly income goes toward essentials such as groceries, school fees, rent, and existing liabilities, collections become highly time-sensitive within the first few days post salary credit.
To maximize recoveries, borrower engagement needed to happen proactively within the first 10 days of the repayment cycle, particularly around T+3, T+5/7 days of the month. However, in a growing ecosystem, the existing collections ecosystem is bound to face multiple operational and scalability challenges:
- Heavy operational overhead: Managing data flows across 200+ agencies involved fragmented file formats, delayed updates, and constant operational coordination.
- Inconsistent recovery performance: Significant variation across agency outcomes made month-on-month efficiency difficult to stabilize and predict.
- Compliance risk at scale: Ensuring RBI-compliant collections practices across multiple external vendors created visibility and monitoring challenges.
- Lack of a tech-first approach: Most collections workflows remained telecalling-heavy and operationally manual, limiting scalability, optimisation, and real-time control.
- Regional borrower behavior differences: Recovery behavior varied significantly across regions, requiring contextual engagement strategies instead of one-size-fits-all collections workflows.
The lender also observed that while industry recovery efficiency in Bx personal loans typically averaged around ~83%, improving outcomes even by 3 to 4% created a significant impact on overall portfolio health and flow rate reduction.
Hence, what was needed was not just another collections vendor, but a single, technology-led partner capable of bringing control, consistency, compliance, and scalability into one unified system.
The Solution: DPDzero’s Approach
DPDzero implemented a digital-first and AI-led collections infrastructure that combined automation, omnichannel borrower engagement, compliance frameworks, and operational intelligence into a unified recovery engine.
Since each borrower's behavior is different, every allocation that flows into DPDzero passes through our in-house Risk Engine that inputs signals such as the last repayment date, previous dispositions, and responsiveness patterns to segment borrowers into cohorts (ranging from R1 to R5), enabling different treatment strategies for each borrower segment. These strategies are a mix of:
Digital-first outreach at scale
DPDzero leveraged almost every digital channel, like WhatsApp communication (WABA), SMS, IVR, Automated digital nudges, and Google RCS. This helped us to engage borrowers proactively during critical salary-cycle windows, helping drive recoveries with lower operational dependency.
Voice AI for intelligent reachouts and follow-ups
Voice AI was deployed to handle high-volume borrower interactions in early buckets and generate borrower intent to pay in late buckets with contextual and personalized workflows. DPDzero’s propensity-driven segmentation identified:
- Borrowers likely to self-cure through a single digital touchpoint
- Borrowers requiring assisted follow-ups
- Accounts needing deeper engagement strategies
This significantly optimized recovery costs while improving borrower reachability and engagement consistency at scale.
Unified Collections Tech platform
DPDzero consolidated fragmented collections operations into a single technology layer that enabled real-time visibility into recovery performance, centralized monitoring, operational control, attribution tracking, and continuous workflow optimization.
The platform also streamlined dependency on multiple collections vendors while creating a more standardized recovery framework.
Compliance by design
Compliance workflows were embedded directly into borrower engagement journeys through RBI-compliant communication frameworks, consent-based standardised outreach, auditable borrower interactions, and much more.
This reduced compliance risk while improving operational governance across collections workflows.
Consistent performance engine
Instead of relying on static recovery strategies, DPDzero continuously optimized collections workflows through:
- AI-led prioritization
- Real-time strategy refinements
- Regional borrower segmentation
- Channel-level performance optimization
This enabled more predictable and stable recovery outcomes month-on-month.
DPDzero ensured the shift was from reactive, operations-heavy collections to a proactive, AI-led recovery engine built for scale, compliance, and consistency.
The Intersection Point
As the lender scaled its lending operations, the need was no longer just higher recoveries, but a collections framework that could scale efficiently, reduce operational dependency, and improve borrower interactions.
DPDzero’s AI-first collections framework enabled:
- Low-cost recoveries through Digital and Voice AI workflows
- Improved borrower engagement without proportional manpower increase
- Reduced dependency on pure telecalling operations
- More proactive recovery behavior during critical salary-cycle windows
The partnership also enabled the lender to focus beyond average recovery metrics and prioritize the reduction of future delinquency flow rates by targeting borrowers who traditionally remained unpaid even after standard collections efforts.
What did DPDzero achieve for the leading fintech?
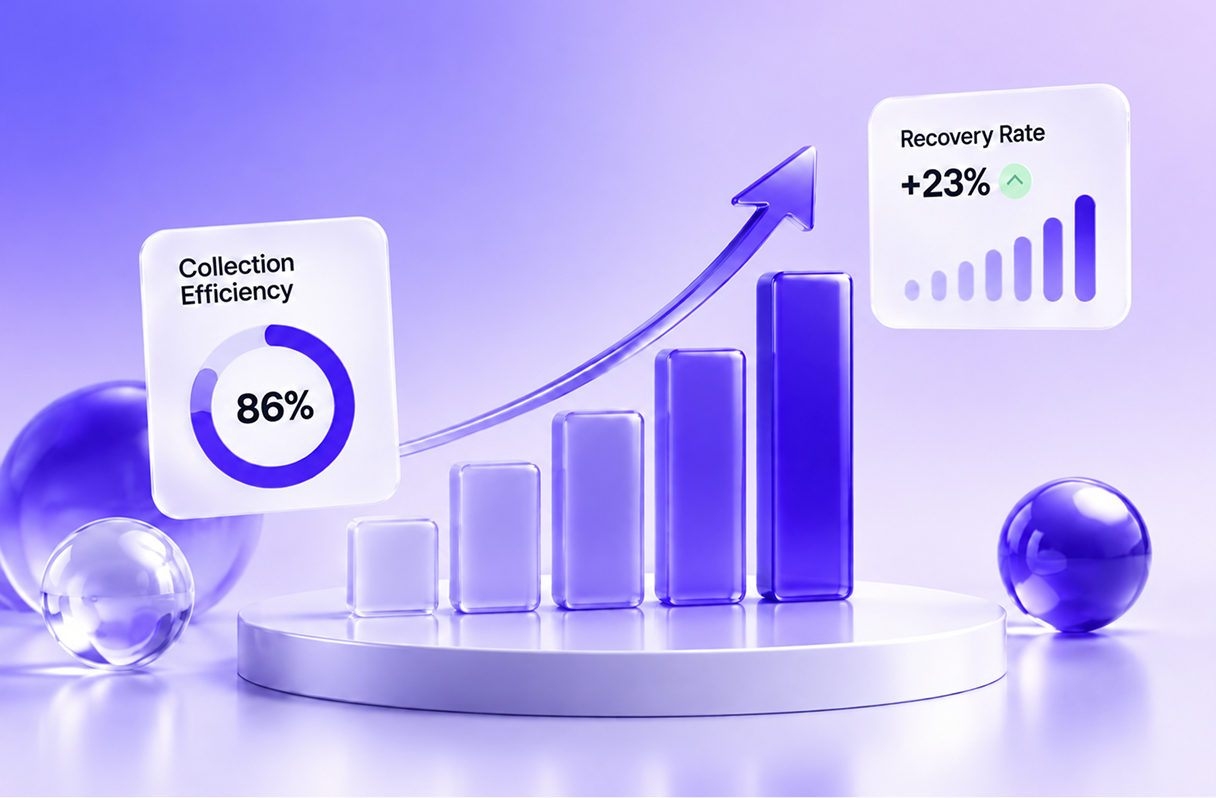
- ~86% Collection Efficiency
- ~84% PTP Conversion Rate
- ~81% Connectivity Rate
- Top 5 out of 200+ Collection Partners
Operational Outcomes
- Faster borrower engagement during salary-credit windows
- Improved borrower responsiveness through omnichannel communication
- Lower manual intervention through AI-led prioritization
- Better segmentation and allocation efficiency
- Increased scalability across regions and borrower types
- Improved recovery consistency across Bx and recovery buckets
- Unified operations across 20+ agency workflows into one streamlined platform
Results & Impact
DPDzero helped the lender transition from a traditional collections-dependent fintech platform towards a more scalable and AI-led recovery infrastructure. What differentiated DPDzero was not just recovery performance, but the ability to operationalise:
- AI-first collections workflows
- Highly contextual borrower segmentation
- Compliant digital engagement
- Proactive recovery strategies at scale
The best part about DPDzero that the lender’s team highlighted was:
- DPDzero’s strong leadership involvement
- High ownership across operational teams
- A consistent focus on improving month-on-month recovery outcomes rather than operating purely as a collections vendor
The partnership also enabled the lender to confidently allocate nearly 20% of its collections portfolio to DPDzero across Bx, DPD30+, and recovery segments due to the platform’s ability to maintain efficiency, compliance, and operational scalability simultaneously.
Lender’s Voice
Their use of digital outreach and AI-powered workflows enabled close to ~84% PTP conversion rates, while giving our teams real-time visibility into performance through a unified dashboard.